For a business owner, a customer who pays regularly can feel like a dependable part of the company’s value.
The relationship has lasted for years. The billing amount is familiar. There is every expectation that next month will look much like this month.
When thinking about a future sale, it is easy to describe that income as recurring revenue and expect it to support an attractive valuation.
But a buyer has to answer a different question: what gives us confidence that this revenue will continue after we acquire the business?
A payment history helps. So do customer retention, service quality and established relationships. Contracts, renewal terms, scope clarity and evidence of delivery help explain how much confidence those expectations deserve.
Without that support, the owner and buyer may be valuing two different things.
The Challenge: The Request That Exposed the Uncertainty
In an actual operating review, a customer asked to put a longstanding service relationship on hold, with the possibility of returning when business activity improved.
Until then, the account had a familiar billing value. Participants described an agreement dating back several years, with no renewal and an unchanged billing amount.
The request prompted questions that the recurring number could not answer.
What notice applied? Which agreement was current? What work remained active? What happened to billing during the hold? Can a restart happen?
During the discussion, one participant noted that the contract copy available to them appeared to carry the provider’s signature without the customer’s. Another referred to a different copy and proposed sharing it.
This did not establish that a fully executed agreement was absent. It established that the document immediately available did not settle the question.
Management called for checking the contract, identifying outstanding work, reviewing the account position and confirming the proposed arrangement in writing.
The relationship was familiar. Its current commercial position still needed reconstruction.
The Approach: Now Put a Buyer in That Conversation
There was no acquisition in this case. But imagine the same questions arising during a sale process.
The owner presents the account as recurring revenue.
The buyer asks for the agreement, renewal provisions, cancellation rights and evidence supporting the current price and scope.
The team must find another contract version, review past correspondence, and speak with the people who remember what was agreed
That does not automatically make the revenue worthless, nor does it erase the income already earned.
It does, however, weaken the argument that future revenue deserves the same confidence as clearly evidenced, durable customer commitments.
A buyer could still value the relationship based on retention history and customer behaviour, but the seller must explain the added uncertainty and may have less evidence to support the premium being requested.
The Impact: How the Uncertainty Can Affect Value
There are two distinct ways this could influence a valuation.
First, the buyer may accept less of the forecast. An owner may assume that an established account will continue at its existing level. If continuation depends on an unconfirmed renewal, an informal understanding or a hoped-for restart, the buyer may use a more cautious assumption. In a revenue-based valuation, that could mean accepting a smaller amount as the dependable recurring base. In an earnings-based valuation, the concern may affect projected sustainable earnings.
Second, the buyer may offer a lower multiple for the risk being assumed. Even where current earnings are accepted, uncertainty about their durability can weaken the case for a premium multiple.
These are possible valuation responses, not automatic deductions. The same risk should not simply be counted twice. Strong retention, diversified customers and convincing delivery evidence may offset some contractual uncertainty.
The owner’s goal is to make the strongest supportable case for both the earnings and their durability.
The Implementation: A Signed Agreement Is Only the Beginning
The value question extends beyond whether a contract can be found.
Does it describe the service actually being delivered? Does the current price match the agreed terms? Can the customer terminate at short notice? Does a change in ownership require consent?
A signed agreement with broad cancellation rights may offer less predictability than its existence initially suggests.
Operational evidence matters too. In separate governance discussions, management asked for operating tasks to be linked to the corresponding scope in the service agreement. That mapping was incomplete and remained open at a later review.
This was a separate workstream, but the lesson is relevant: a buyer needs confidence that the business understands, and can consistently fulfil, the promises supporting its revenue.
Build the Evidence for the Valuation You Want
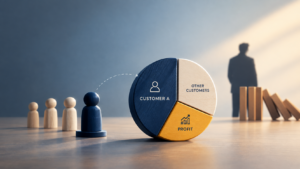
Start with the relationships that contribute most to revenue and profit. For each, assemble:
The current agreement, amendments and evidence of approval.
Pricing, scope, renewal, termination and relevant transfer provisions.
Delivery records supporting the service being charged.
Retention history, unresolved disputes and material commercial changes.
A clear explanation of what future revenue assumes.
Then ask someone outside the account team to explain why the relationship should continue. If the explanation depends mainly on the owner’s memory or reassurance, the valuation argument still needs work.
Closing Context
The case did not end with a documented sale or quantified loss. It exposed a gap between a familiar billing amount and the evidence needed to explain its future.
For an owner building towards an exit, that gap deserves attention long before a buyer discovers it.
If you want a buyer to pay for dependable recurring revenue, build the evidence that makes it dependable.
If you’re planning an exit in the next 1 to 3 years, the fastest way to find out where your revenue story has gaps like this is a 30-minute recurring revenue readiness review.
Book a slot