Customer concentration risk can be far more dangerous than your revenue reports suggest.
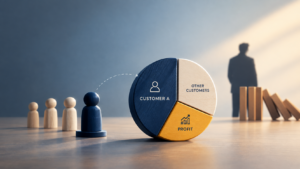
A founder thought his largest customer represented a manageable 30% of annual revenue. Mathematically sound. Economically dangerous.
When we analyzed gross profit instead of revenue, the same customer represented 60% of total profit. Worse, the relationship hinged entirely on the founder’s involvement.
This business had three concentration problems hiding inside one customer.
Revenue Concentration vs. Economic Concentration: What Your Numbers Are Really Saying
The Revenue View (What You Probably Think You Know)
Consider a professional-services company generating ₹10 crore in annual revenue:
| Customer Group | Revenue | % of Revenue |
|---|---|---|
| Customer A | ₹3.0 cr | 30% |
| Customers B–D | ₹3.5 cr | 35% |
| Remaining customers | ₹3.5 cr | 35% |
| Total | ₹10.0 cr | 100% |
Customer A looks important but manageable. 70% of revenue comes from elsewhere.
The Gross Profit View (What Actually Matters)
Now look at what each customer contributes after direct delivery costs:
| Customer Group | Revenue | Gross Profit | % of Total GP |
|---|---|---|---|
| Customer A | ₹3.0 cr | ₹1.20 cr | 60% |
| Customers B–D | ₹3.5 cr | ₹0.50 cr | 25% |
| Remaining customers | ₹3.5 cr | ₹0.30 cr | 15% |
| Total | ₹10.0 cr | ₹2.00 cr | 100% |
The same customer now represents 60% of economics.
Why the gap?
Revenue doesn’t account for customer servicing costs. Two customers can each generate ₹50 lakh in revenue:
- One requires heavy staffing, management attention, rework cycles, and ongoing support
- The other runs on mature processes with lean delivery
The revenue is identical. The value to the business isn’t.
The Math That Breaks Most Businesses
What Happens If You Lose Your Largest Customer
Assume your company carries ₹1.2 crore of annual fixed overhead (salaries, systems, office, finance, HR).
Before losing Customer A:
- Gross profit: ₹2.00 crore
- Overhead: ₹1.20 crore
- Operating profit: ₹80 lakh
After losing Customer A (before restructuring):
- Gross profit: ₹0.80 crore (remaining customers only)
- Overhead: ₹1.20 crore (doesn’t disappear overnight)
- Operating loss: ₹40 lakh
You lost 30% of revenue.
You moved from an ₹80 lakh profit to a ₹40 lakh loss.
This is why revenue concentration hides the true fragility of a business.
The Third Concentration Problem: Key-Person Risk
We asked the owner one more question: Who actually owns Customer A?
Legally? The company.
Operationally? The founder.
- He originated the relationship
- Senior conversations default to him
- He negotiates major deals
- He’s the escalation point when problems arise
The team could deliver the work. But the relationship depended materially on him.
Now the business had three different risk profiles:
| Risk Type | Concentration Level |
|---|---|
| Revenue concentration | 30% |
| Economic concentration | 60% of gross profit |
| Key-person concentration | Founder-dependent relationship |
For a potential buyer, key-person risk is the most uncomfortable question: Will this customer stay when the founder leaves?
How Concentration Affects Your Business Valuation
Owners often assume concentration should trigger a simple price deduction—like discovering unpaid taxes or broken equipment.
It doesn’t work that way.
Concentration changes the buyer’s confidence in future earnings.
Imagine your company produces ₹80 lakh of sustainable operating profit. An otherwise transferable business might justify a 5× earnings multiple.
That implies a value of ₹4 crore.
But if 60% of gross profit comes from one customer—and that relationship depends heavily on the founder—a buyer won’t pay the same multiple.
The question isn’t: “How much should I deduct for this customer?”
It’s: “How many years of earnings am I paying upfront when those earnings may not transfer?”
Result: Lower multiples, earn-out provisions, retention clauses, or requirements that the founder stay through transition.
The Two-Minute Test: Identify Your Concentration Risk Now
You don’t need a valuation model. Run this diagnostic:
Step 1: Calculate Revenue Concentration
Largest customer revenue ÷ Total revenue = X%Step 2: Calculate Gross-Profit Concentration
Gross profit from largest customer ÷ Total gross profit = Y%Step 3: Compare the Numbers
If your largest customer is:
- 20% of revenue AND 22% of gross profit → Similar risk levels
- 20% of revenue BUT 45% of gross profit → Your revenue report is hiding economic concentration
Step 4: The Relationship Question
Ask yourself: Who does this customer trust?
Not who sends invoices or delivers work. Who does the customer actually trust?
If the answer is you (the founder/owner), ask one more:
“If I disappeared from this business tomorrow, would this customer behave differently?”
If yes, you have overlapping customer concentration and key-person concentration.
The Diversification Trap: Why “More Customers” Doesn’t Solve This
Suppose your ₹10 crore company adds ₹2 crore of low-margin work.
Revenue rises to ₹12 crore. Customer A drops from 30% to 25% of revenue.
On paper, concentration improves.
But if the new ₹2 crore contributes minimal gross profit, Customer A may still represent close to 60% of your company’s economics.
The percentage improved. The risk didn’t.
Real diversification requires three things:
- Profitable customers (not just more revenue)
- Transferable relationships (not founder-dependent)
- Customer perception of institutional strength (not founder + team)
This means:
- Introducing other senior people into relationships
- Documenting commercial history and processes
- Building clear escalation routes beyond the founder
- Gradually moving customer trust from individual to organization
This takes time. Which is why concentration is nearly impossible to fix six weeks before an exit.
The Bottom Line: Three Metrics Every Owner Should Track
Revenue concentration: How dependent your sales are on one customer
Gross-profit concentration: How dependent your economics are on one customer
Key-person concentration: Whether those economics belong to the business or the owner
Take your largest three customers and track all three:
| Customer | % of Revenue | % of Gross Profit | Primary Relationship Owner |
|---|---|---|---|
| A | 30% | 60% | Founder |
| B | 20% | 18% | VP Sales |
| C | 15% | 12% | Account Manager |
If one customer dominates the second column and your name dominates the third column, you haven’t just found a customer-concentration problem.
You’ve found a business that may not transfer.
That’s the real cost of concentration—not just risk, but a ceiling on what your business is actually worth.
What’s Next?
Understanding concentration is the first step. Managing it requires:
- Systematic customer profitability analysis
- Deliberate relationship transfer from founder to team
- Strategic diversification into higher-margin segments
- Clear governance and escalation frameworks
The earlier you address it, the less disruptive and the higher your exit valuation.